


 You have successfully registered
 Certified
📘 Course Overview
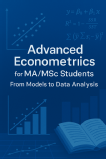
Advanced Econometrics for MA/MSc Students: From Models to Data Analysis
📖 Course Description
This intensive graduate‐level course is tailored for MA and MSc students eager to deepen their understanding of econometric theory and master empirical analysis techniques. Building on foundational regression methods, you’ll explore advanced topics—GMM estimation, panel‐data frameworks, multivariate time‐series (ARIMA, VAR), and limited dependent‐variable models (logit, probit)—all within a hands‐on, data‐driven environment.
Whether you’re preparing for a thesis, academic research, or policy analysis, this course equips you to bridge theory and practice: formulating hypotheses, selecting appropriate models, diagnosing estimation issues, and communicating robust results.
✅ What This Course Offers
- In‐Depth Coverage of Advanced Topics
- Generalized Method of Moments (GMM) & Instrumental Variables
- Panel Data Techniques (Fixed & Random Effects, Dynamic Panels)
- Time‐Series Models (AR, MA, ARMA, VAR, Cointegration)
- Limited Dependent Variable Models (Logit, Probit, Tobit)
- Step‐by‐Step Conceptual Development
Complex derivations and assumptions unpacked with real‐world economic and financial examples. - Hands‐On Analysis with Professional Software
Implement every technique in R, Python—data cleaning, estimation, diagnostics, and visualization. - Balanced Pace & Structure
Two 90‑minute sessions per week to cover theory, demonstrations, and Q&A without overload. - Bilingual Support (Hindi + English)
Clarify technical terminology and intuition in both languages for maximum comprehension. - Regular Assignments & Research‑Style Project
Weekly problem sets and a capstone empirical project to apply methods on real datasets and produce a research‑grade report.
🎯 Who This Course Is For
- MA/MSc students aiming to elevate their econometric toolkit for thesis work or publications.
- Aspiring researchers and policy analysts who need rigorous training in advanced estimation methods.
- Anyone preparing for competitive exams or academic interviews requiring high‑level quantitative skills.
🎓 By the End of the Course, You Will
- Confidently select and implement advanced econometric models for diverse research questions.
- Diagnose and address issues like endogeneity, heteroskedasticity, and autocorrelation.
- Utilize GMM, panel‑data estimators, and time‑series techniques with professional software.
- Translate empirical results into clear, policy‑relevant insights and research outputs.



 View this Course



 Certified




